A federal tax evasion investigation is a criminal probe by the IRS Criminal Investigation division into whether someone willfully tried to dodge a tax they legally owed. It is not an audit.
Table of Contents
- What a Federal Tax Evasion Investigation Actually Means
- The IRS Criminal Investigation Process: From Referral to Indictment
- IRS Special Agent Interview Rights: What You Must Know Before You Speak
- 26 U.S.C. 7201 Defense Strategies: Elements the Government Must Prove
- When to Hire a Tax Fraud Attorney (And Why Timing Matters)
- Digital Evidence and Forensic Accounting: What Investigators Already Have
- The Psychological Toll: Managing Stress During a Federal Investigation
- Frequently Asked Questions
Last Updated: October 6, 2026
What a Federal Tax Evasion Investigation Actually Means
Most people confuse the two. An audit asks, "Did you make a mistake?" A criminal investigation asks, "Did you commit a crime?" That distinction changes everything about how you respond.
This confusion can cost people dearly. A taxpayer treats a special agent's visit like a routine audit, answers questions freely, and hands the government its case.
The IRS Criminal Investigation division, often called CI, handles these cases. Special agents carry firearms, serve warrants, and work with the Department of Justice.
So what should you do? Stop talking. Call a lawyer. That single move protects more than any explanation you could offer.
The IRS Criminal Investigation Process: From Referral to Indictment
The IRS criminal investigation process moves through a clear sequence: referral, evaluation, investigation, and referral to prosecutors. Understanding the path helps you see where you stand.
It usually starts quietly. A civil auditor notices something odd. A tip comes in. A bank reports a large cash transaction under the Bank Secrecy Act. CI reviews these referrals and decides which ones deserve a full probe.
Once a case is opened, special agents gather evidence for months, sometimes years. They pull bank records, interview witnesses, and trace money. You may not know you are a target until they contact you.
If agents believe a crime occurred, they send a referral to the Department of Justice. Federal prosecutors then decide whether to seek an indictment from a grand jury.
How Special Agents Build a Case
Agents build a case by proving intent, not just numbers. They look for patterns that show you knew what you were doing.
- Underpayment of tax: You owed more than you paid.
- Affirmative act: You did something to hide it, like keeping two sets of books.
- Willful attempt: You meant to evade, not just made an error.
That third element is where most cases rise or fall. Agents hunt for evidence of intent through emails, notes, and witness statements. Forensic accounting ties the money trail together.
This is the part most people underestimate. By the time agents knock on your door, they often already have a file. Your job is not to fill in the blanks for them.
IRS Special Agent Interview Rights: What You Must Know Before You Speak
You have the right to remain silent, the right to an attorney, and the right to stop an interview at any time. Special agents must respect these rights. What you say before invoking them can still hurt you.
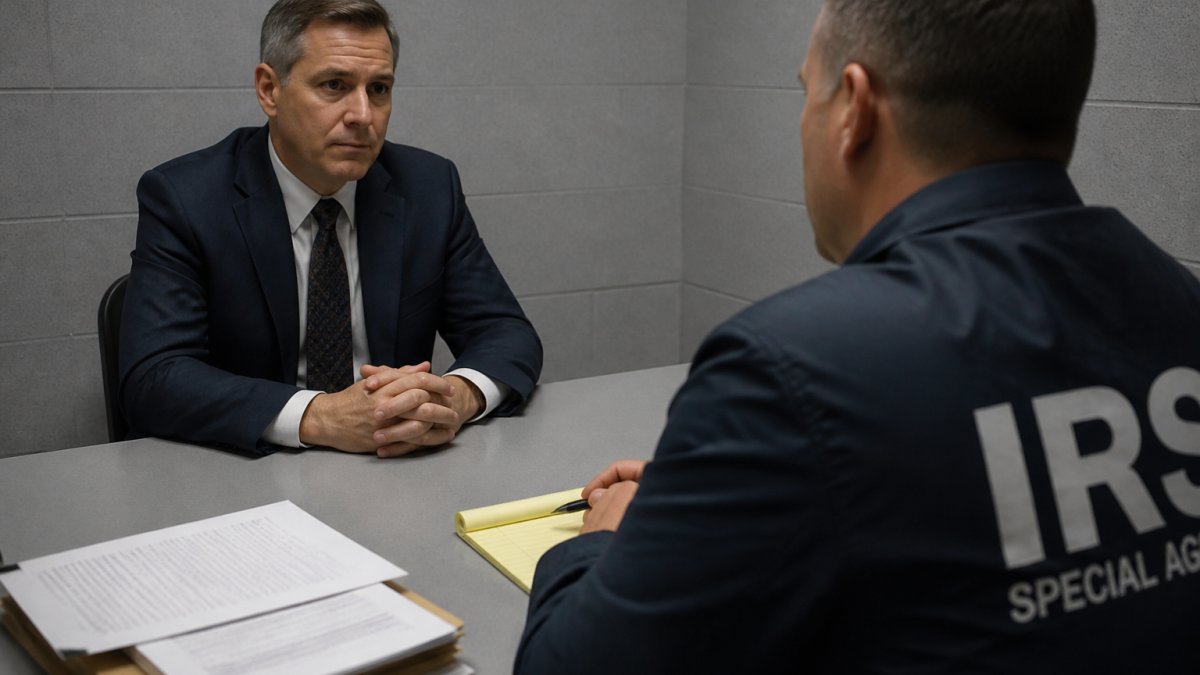
Many people think that if they just explain the situation, everything will be fine. That instinct is dangerous. Agents are trained to build rapport and get you talking. A casual comment can become evidence.
Here is what you control:
- You can decline to answer questions.
- You can say, "I want to speak with my attorney first."
- You can end the interview once it starts.
Once you ask for a lawyer, questioning must stop. That protection is not a loophole. It is a basic right, and using it is smart, not suspicious.
26 U.S.C. 7201 Defense Strategies: Elements the Government Must Prove
Under 26 U.S.C. 7201, the government must prove three things: a tax deficiency, an affirmative act of evasion, and a willful attempt to evade. Miss any one of these, and the charge fails.
That structure is your defense. Each element is a hurdle prosecutors must clear, and a skilled attorney attacks every one.
Tax deficiency means you owed more tax than you reported. But a deficiency alone is not a crime. People make honest mistakes all the time.
Affirmative act means you did something to hide the tax. Simply failing to file is usually not enough. The government needs a concrete step, like falsifying records, hiding income, or concealing assets.
Willfulness is the hardest element to prove. Prosecutors must show you knew your duty and chose to break it. Confusion, bad advice, or a genuine misunderstanding can defeat this element.
Penalties Under 26 U.S.C. 7201
A conviction under 7201 is a felony. The statute authorizes a fine of up to $100,000 for individuals (up to $500,000 for corporations), imprisonment of up to five years, or both, plus the costs of prosecution. The court can also order restitution for the tax loss.
That is separate from the civil side. The IRS can still assess the unpaid tax, accuracy-related penalties, and interest, even if the criminal case ends in acquittal. Civil and criminal exposure run on parallel tracks.
How 7201 Differs From 7203
Many people charged with tax crimes are actually charged under 26 U.S.C. 7203, which covers willful failure to file a return, supply information, or pay tax. That is a misdemeanor, with a maximum of one year in prison and a $25,000 fine for individuals.
The distinction matters. A 7201 charge requires the government to prove an affirmative act of evasion on top of willfulness. A 7203 charge does not. Prosecutors sometimes use 7203 as a lesser included offense or as leverage in plea negotiations.
Defense Theories That Actually Work
A strong defense is not a single argument. It is a set of challenges aimed at the weakest element in the government's case.
- Lack of willfulness. If you relied in good faith on a competent tax professional, or if you genuinely misunderstood an ambiguous rule, the willfulness element can fail. This is the most common defense in criminal tax cases.
- No affirmative act. If the government can only show you underpaid, not that you took a step to conceal it, the 7201 charge may not stand.
- Reliance on counsel. Good-faith reliance on an attorney or CPA's advice can negate willfulness, provided you gave that professional complete and accurate information.
- Statute of limitations. The general limitations period for tax evasion is six years from the date of the offense. If the government waited too long, the charge can be barred.
- Improper venue or procedure. Federal criminal procedure rules give you the right to be tried in the district where the offense occurred, and defects in the grand jury or charging process can be challenged.
- Fifth Amendment issues. If statements were obtained in violation of your rights, your attorney can move to suppress them.
Your attorney will examine every element and look for gaps. Sometimes the government cannot prove willfulness. Sometimes the affirmative act is weak. A good defense exploits those weaknesses early, often before an indictment is ever returned.
When to Hire a Tax Fraud Attorney (And Why Timing Matters)
Hire a tax fraud attorney the moment you learn you are under investigation, not after charges are filed. Early representation shapes the entire case.
The reason is simple. The government's case gets stronger with every day you wait. Witnesses talk. Records get subpoenaed. Statements get made that cannot be undone.
An attorney steps in and takes control of the communication. Agents must go through your lawyer, not directly to you. That alone prevents costly mistakes.
Timing also affects your options. Early on, an attorney can explore a voluntary disclosure, which may reduce exposure.
Criminal tax defense is not a DIY project. The stakes include incarceration, restitution, and fines and penalties.
If you are in northern Colorado and facing questions from federal agents, our firm has defended clients in these courts since 1975. We know how these cases unfold.
Digital Evidence and Forensic Accounting: What Investigators Already Have
Investigators rarely start from scratch. By the time they contact you, they often have bank records, digital files, and a forensic accountant's analysis already in hand.
This is where modern tax cases differ from the old ones. Money leaves a digital trail. Every transfer, deposit, and payment can be traced.
Agents use forensic accounting to reconstruct your finances. They compare what you earned against what you reported. Gaps become the backbone of their case.
They also gather digital evidence:
- Bank statements and wire records
- Emails and text messages
- Social media posts showing spending
- Business and personal financial software data
That last category surprises people. Your own accounting software can become evidence. So can a casual post about a new car or a vacation.
The government may also use an IRS summons or a grand jury subpoena to compel records from third parties.
What most guides miss is this: you cannot delete your way out of a digital case. Destroying records can be charged as obstruction and makes everything worse.
The Psychological Toll: Managing Stress During a Federal Investigation
A federal investigation is one of the most stressful events a person can face. The uncertainty, the fear of prosecution, and the worry about family and career can feel overwhelming.
That stress is real, and ignoring it does not help. It can cloud your judgment at the exact moment you need to think clearly.
Here is what helps:
- Get legal help early. Knowing someone is protecting your rights lowers the panic.
- Lean on trusted people. Isolation makes everything worse.
- Avoid discussing the case. Talk to your attorney, not to friends or coworkers.
- Focus on what you control. You cannot control the investigation. You can control your response.
The fear of losing a career or reputation is common, and it is understandable. Many people worry the case will follow them forever.
You do not have to face this alone. That is not a slogan. It is the practical difference between a case handled well and one handled in fear.
A federal tax evasion investigation is frightening, but it is not hopeless. The worst outcomes usually happen when people face agents alone and say too much. At the Law Offices of Robert E.
Frequently Asked Questions
What is the difference between a civil tax audit and a criminal tax evasion investigation?
A civil audit is handled by IRS examiners and typically results in a tax deficiency, penalties, and interest. A criminal investigation is conducted by IRS Criminal Investigation special agents who are building a case for federal prosecution under statutes like 26 U.S.C. 7201. The key difference is intent: criminal cases require proof of a willful attempt to evade tax, not just an underpayment. If a special agent contacts you, the matter has moved beyond a civil audit.
What triggers an IRS Criminal Investigation?
IRS Criminal Investigation cases often begin with a referral from a civil audit, a tip from a whistleblower or former associate, suspicious activity reports filed under the Bank Secrecy Act, or patterns flagged during routine compliance reviews. Large cash transactions, unreported foreign accounts, and discrepancies between reported income and lifestyle can also draw scrutiny. Once a referral is accepted, special agents gather evidence before approaching the target.
Do I have the right to remain silent during an IRS special agent interview?
Yes. You have the right to decline an interview and to have an attorney present. Special agents are trained to conduct non-custodial interviews that feel conversational, but anything you say can be used against you in a federal prosecution. Politely state that you wish to consult a tax fraud attorney before answering any questions. Do not provide documents or explanations on the spot, even if you believe they are harmless.
How long does the IRS have to bring criminal tax evasion charges?
Under federal law, the statute of limitations for most tax evasion offenses is six years from the date the return was due or filed, whichever is later. The government can extend this in certain circumstances, such as when a return is deemed false or fraudulent. If you believe you are under investigation, an attorney can assess where you stand relative to the limitations period and what steps to take.